

How to assess commercial property cash flow
Commercial property cash flow reveals whether an investment can produce reliable income after its operating costs, financing, and vacancy risks are accounted for. A building may appear attractive because of its purchase price or headline rent, yet the real value lies in the money that remains available to the owner each month and year. By reviewing income carefully and testing realistic assumptions, you can make decisions based on performance rather than optimism.
Start with the property’s potential rental income
The assessment begins with gross potential rent, which is the income the property could generate if every unit or floor were occupied and every tenant paid in full. For a single-let office or warehouse, this figure may be straightforward. For a retail parade, industrial estate, or multi-let business centre, calculate the rent from each occupier separately.
Review the following details before relying on quoted rent:
- Current rent per tenant and lease start date
- Rent review dates and break clauses
- Lease expiry dates
- Rent-free periods or stepped-rent agreements
- Service charge arrangements
- Outstanding rent arrears
- Tenant incentives, such as fit-out contributions
A property with a high contracted rent is not automatically a strong investment. A tenant approaching a break date may leave, while a rent level above local market rates may be difficult to sustain at renewal. Compare current rents with recent transactions for similar premises in the same area.
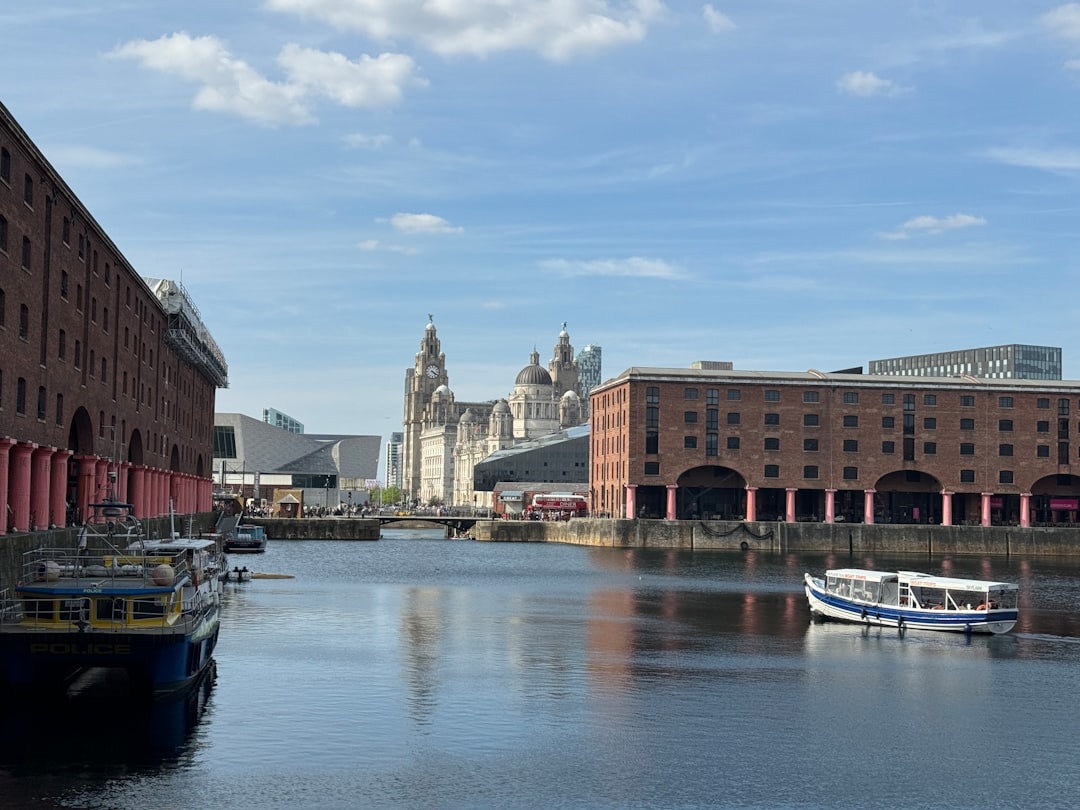
When considering acquisition routes, Property Buying Process in Liverpool Explained can help you place financial due diligence within the wider purchase timetable.
Allow for vacancies and credit losses realistically
Effective gross income is lower than potential rent because commercial properties do not remain fully occupied forever. Even a well-let building can face a void when a tenant relocates, fails, or negotiates a rent-free period during renewal.
Use a vacancy allowance that reflects the type of property, its location, and local demand. For example, a modern logistics unit in a sought-after employment zone may justify a lower allowance than an older office building with a limited tenant pool. You should also budget for non-payment risk, particularly where tenants are small businesses or operate in volatile sectors.
A simple formula is:
Effective gross income = potential rent minus vacancy allowance minus bad debt allowance
Consider a property with annual potential rent of £120,000. If you allow 8% for voids and 2% for bad debts, effective gross income becomes £108,000 before operating expenses. This adjustment can materially change the return you expect from the purchase.
Separate recoverable costs from owner-paid expenses
Commercial leases vary considerably. Under a full repairing and insuring lease, many costs can be passed to the tenant. Under shorter or more flexible arrangements, the landlord may pay for repairs, management, insurance, utilities in common areas, and periodic upgrades.
Create a line-by-line operating expense forecast. Typical owner costs include:
- Property management fees
- Building insurance and public liability cover
- Repairs and planned maintenance
- Professional fees and legal costs
- Service charge shortfalls
- Marketing and letting agent fees
- Business rates during void periods
- Compliance, fire safety, and energy performance work
Do not assume service charges cover every expense. Check the service charge budget, any caps in leases, historic shortfalls, and whether major works are recoverable. Older buildings can require substantial capital expenditure for roofs, heating systems, lifts, or accessibility improvements.
Your net operating income is calculated by subtracting ordinary operating expenses from effective gross income. This figure is one of the clearest measures of a property’s ongoing income strength.
Review lease structure and tenant quality together
Cash flow depends on more than rent. It also depends on who pays it, for how long, and under what contractual terms. A long lease to a financially robust tenant can support predictable income, while a multi-let property may offer diversification but require more active management.
Assess each tenant’s trading history, accounts, credit profile, sector exposure, and parent-company support where relevant. Check whether a personal guarantee, rent deposit, or guarantor is in place. For retail and hospitality occupiers, local footfall and trading conditions may deserve added scrutiny.
The legal structure also affects your exposure to repairs and reletting costs. How commercial leasing differs from property ownership provides useful context when reviewing the responsibilities that remain with the landlord.
Include financing costs and capital demands
Net operating income is not the same as cash in your bank account. If you use a commercial mortgage, deduct interest payments, loan fees, valuation costs, and any arrangement charges. A property can have a healthy yield but still produce weak cash flow if debt costs are high.
Calculate annual debt service and compare it with net operating income. The result is the debt service coverage ratio:
Debt service coverage ratio = net operating income divided by annual debt service
Lenders often prefer a ratio above 1.25, though requirements vary. A ratio of 1.50 means the property generates £1.50 of operating income for every £1.00 needed to service debt. Test the result against higher interest rates, reduced occupancy, and delayed rent reviews.
Set aside funds for capital expenditure as well. Replacing a roof or modernising mechanical systems may not occur every year, but these costs should be reflected in a long-term cash flow forecast.
Test local market assumptions before committing
Your forecast should reflect the specific market rather than broad national averages. Rental growth, lease-up periods, tenant demand, and redevelopment plans can differ markedly between districts.
For location-led research, review the Neighborhood Profiles of Liverpool - Local Lifestyle Insights alongside commercial comparables, transport access, nearby employers, and planned infrastructure. A strong local employment base can support demand, but supply pipelines may limit future rental growth.
Build three scenarios: conservative, expected, and optimistic. The conservative case should assume a longer void period, higher repairs, and limited rental growth. If the investment only works under optimistic assumptions, the margin for error may be too narrow.
A disciplined forecast supports stronger investment choices
A practical commercial property cash flow review should leave you with a transparent annual and monthly forecast, supported by lease evidence and realistic cost assumptions. Focus on the income you can retain, not simply the rent stated in marketing material.
Key points to retain include:
- Potential rent is not the same as collectible income.
- Vacancy, arrears, incentives, and void-period rates can reduce returns significantly.
- Operating expenses and capital works need separate, realistic allowances.
- Tenant strength and lease terms shape the reliability of future payments.
- Debt service coverage helps you judge whether financing remains affordable.
- Conservative scenarios provide a clearer view of downside risk.